| Dow Jones | 53,185 |
| S&P 500 | 7,686 |
| Nasdaq | 26,370 |
| 2 Yr Treasury | 4.34% |
| 10 Yr Treasury | 4.75% |
| 10 Yr Municipal | 3.38% |
| High Yield | 7.02% |
| Dow Jones | 10.66% |
| S&P 500 | 12.28% |
| Nasdaq | 13.46% |
| MSCI-EAFE | 11.77% |
| MSCI-Europe | 8.87% |
| MSCI-Far East | 18.96% |
| MSCI-Emg Mkt | 22.43% |
| US Agg Bond | -0.31% |
| US Corp Bond | -0.40% |
| US Gov’t Bond | -0.45% |
| Gold | 4,497 |
| Silver | 67.24 |
| Oil (WTI) | 86.25 |
| Dollar / Euro | 1.15 |
| Dollar / Pound | 1.35 |
| Yen / Dollar | 160.09 |
| Canadian /Dollar | 0.71 |
Macro Overview
Continued interruptions in the Strait of Hormuz, along with rising tensions with Iran, heightened inflationary pressures and instilled unease among global markets. Rising expectations of Federal Reserve rate hikes coupled with fiscal deficit concerns drove long-term Treasury yields to multi-year highs in August.
GDPNow data released by the Federal Reserve Bank of Atlanta forecasts GDP growth of 4.6% in the third quarter of this year. The estimates are reflective of an expanding economy with manufacturing and construction on the rise nationwide. The robust projections could be considered inflationary by the Federal Reserve should economic expansion prove to be lasting.
Frustration seems to be growing with consumers, as gasoline reached an average of $4.20 per gallon nationally at the end of August. Gasoline prices had fallen to an average of $3 per gallon in early February with the hope of a resolution to the Iranian conflict then.
Global bond yields rose in August, as elevated debt concerns mounted with continued government borrowing. Japan, Germany, Britain, and France saw their government bond yields rise concurrently with U.S. Treasury bond yields. Global bond yields reached their highest levels in nearly 20 years, while the yield on the 30-Year Treasury reached over 5.3%, the highest since 2007.
U.S. National Debt reached $40 trillion in August, increasing by over $3 trillion in the past year. Higher short-term interest rates have added considerable constraint to government efforts in mitigating rising debt levels. Fiscal initiatives have also contributed to excess borrowing and rising debt loads, a burden to budgetary mandates and parameters.
Economic activity in the manufacturing sector expanded in July for the seventh consecutive month according to the most recent data from the ISM Manufacturing PMI Report. An escalation of manufacturing has resulted from data center expansion and construction as well as energy-related manufacturing to satisfy the growing demand for electricity and natural gas.
Companies are paying for consumer data in order to have vast amounts of data analyzed to better train AI models which help determine the behavior and characteristics of consumer behavior.
Bond markets are reacting to a growing demand for funds by U.S. companies and the federal government. The expanding need for capital is driving borrowing costs steeper for companies and the government, in the form of higher bond yields. Rising rates are trickling down to consumers in the form of elevated mortgage and auto loan rates.
Many economists believe that the proliferation of AI has begun to affect wages. Average hourly earnings rose at the slowest pace in August since 2021, along with the largest increase in the average amount of hours worked in two years. Companies are expected to benefit as the integration of AI results in profit expansion and lower employment costs.
Sources: BLS, Federal Reserve, Treasury Dept., ISM, Dept. of Energy
Treasury Yields Rise In August – Fixed Income Overview
Yields on 30-year U.S. Treasuries rose to the highest since 2007 this past month, driven higher by inflationary concerns and better than expected employment data levels.
The Treasury Department stepped in to help stabilize the Japanese yen, the first U.S. intervention to buy the yen since 1998. The U.S. has an interest in assisting to fortify the yen because Japan is the largest foreign holder of U.S. government securities.
Several Federal Reserve members exhibited an intent to raise rates in September if inflationary pressures don’t recede. Fed members are increasingly divided about the direction of rates.
Source: U.S. Treasury
Equities Struggle To Rebound – Equity Markets Overview
A resurgence of hostilities in the Strait of Hormuz drove equity volatility higher in August as the transport of oil became further restricted, sending oil prices higher. As a result, the S&P 500 energy sector has outperformed all other sectors in August and since the beginning of the year.
Better than expected earnings for many U.S. companies as well as consistent growth has helped mitigate some volatility and contributed to fortifying sectors such as manufacturing and energy.
For the second consecutive month, mid cap and small cap stocks underperformed larger cap stocks, traditionally the case when interest rates are rising. The cost to borrow for mid and small cap companies increases as rates rise, yet larger cap companies aren’t as affected due to more sizable balance sheets and cash flow.
Sources: S&P, Bloomberg
How Companies & The U.S. Government Are Competing For Capital – Capital Markets Overview
U.S. government borrowing has been increasing simultaneously as U.S. companies have ramped up funding needs for massive expansion and buildouts for AI infrastructure.
The challenge for the U.S. government is the cost of carrying $40 trillion in existing debt, which currently exceeds $1 trillion per year just in interest payments alone. A fiscal deficit of roughly $2 trillion is adding to the debt burden, as government revenue is being dwarfed by massive expenditures. So in order to continue funding the shortfall, the government borrows funds in the form of selling Treasury bonds.
Meanwhile in the private sector, U.S. companies have embarked on an enormous borrowing campaign to fund nearly 800 billion dollars in infrastructure projects for the buildout of AI infrastruture nationwide. These companies, as well as the U.S. government, have to issue and sell bonds to pay for these huge capital expenditures.
As markets bring buyers and investors together, a shopping spree materializes, with companies and the government competing for funds by selling bonds. As more bonds are offered, the cost of borrowing essentially increases for both the U.S. government and companies.
Sources: Treasury Dept., Congressional Budget Office
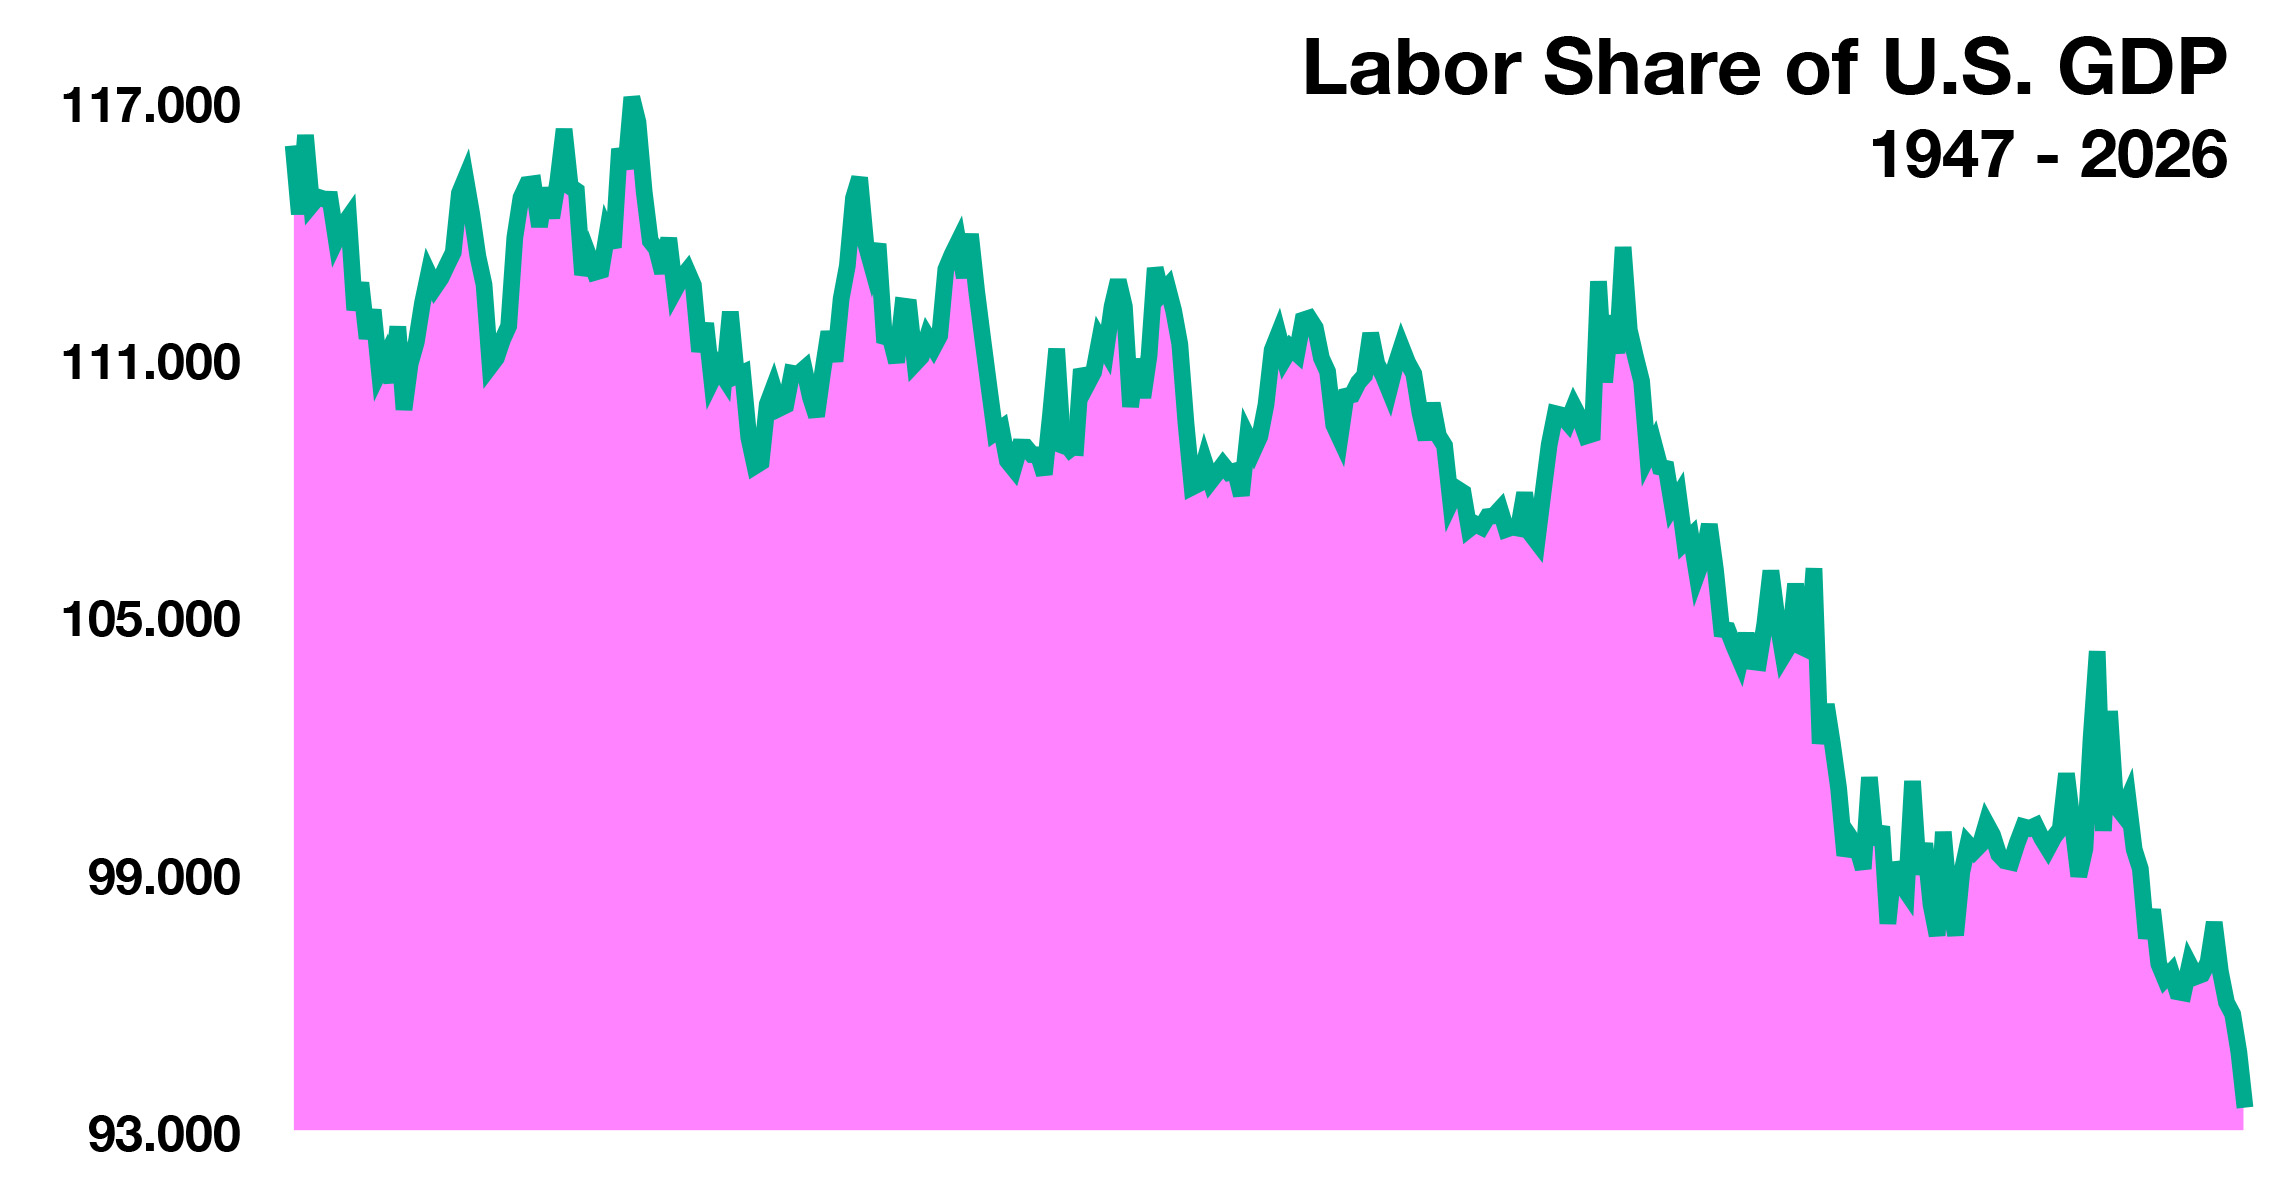
Labor Share Of GDP Lowest Since 1947 – Employment Market Update
The portion of a nation’s economic output (GDP) that goes to workers as wages, salaries, and benefits rather than going to capital owners and shareholders is recognized as the labor share of GDP. The gauge, which began in 1947, has been trending down since a spike in 2020 at the height of the pandemic. How much trickles down to U.S. workers from economic activity determines the future viability of consumers and businesses.

Recent progression with integrating AI into corporate labor ranks has begun to curtail hiring trends throughout numerous industries. As companies adopt AI into certain tasks and employment positions, employees have fewer chances of wage increases and career advancements.
In theory, AI could lead U.S. workers in becoming more efficient and productive, which could become a catalyst for faster economic growth allowing both employees and businesses to earn more without triggering inflation. Conversely, if corporations decide they can boost profits by replacing workers with AI, then there might eventually be fewer positions and downward pressure on wages. (Sources: Labor Dept., BLS)
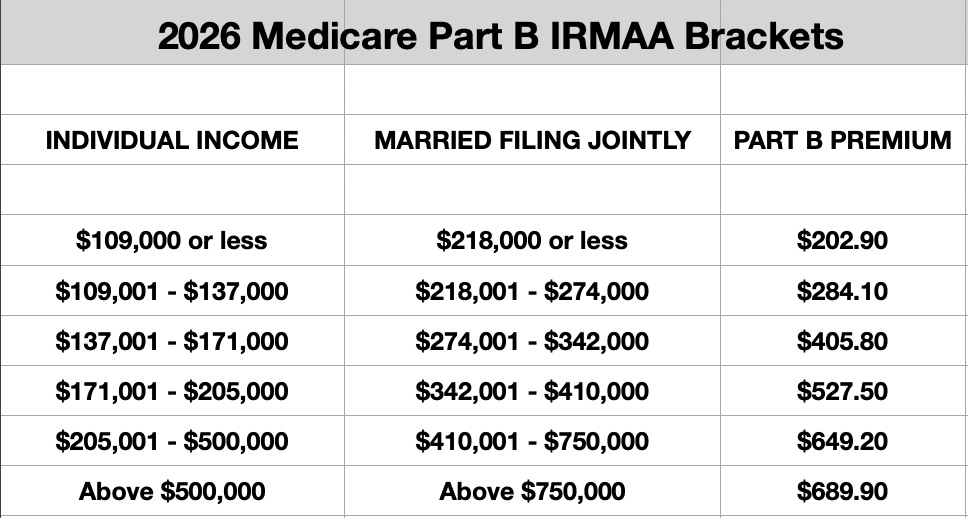
How IRMAA Affects Your Medicare Premium – Medicare & Social Security Update
Medicare premium adjustments are affecting many more retirees, and its a good idea to be aware of income thresholds each year. The adjustment, known as Income Related Monthly Adjustment Amount (IRMAA), is essentially an extra Medicare charge paid by income earners above certain thresholds. It affects participants who have Medicare Part B and/or Part D coverage. The IRMAA is a surcharge in addition to the monthly Medicare premium paid each month.

The IRMAA is determined using the modified adjusted gross income (MAGI) from your federal tax return. The determination is made using the prior tax return from two years earlier. So an IRMAA in 2026 would be based on a 2024 federal tax return. MAGI for the purpose of calculating the IRMAA includes the adjusted gross income plus tax-exempt interest income.
Conversely, Medicare participants that have a decrease in income may request a re-calculation in order to adjust the IRMAA to be eligible for a lower Medicare premium surcharge. A one time realization of capital gains can also affect the IRMAA resulting in a higher premium. (Sources: Social Security Administration)
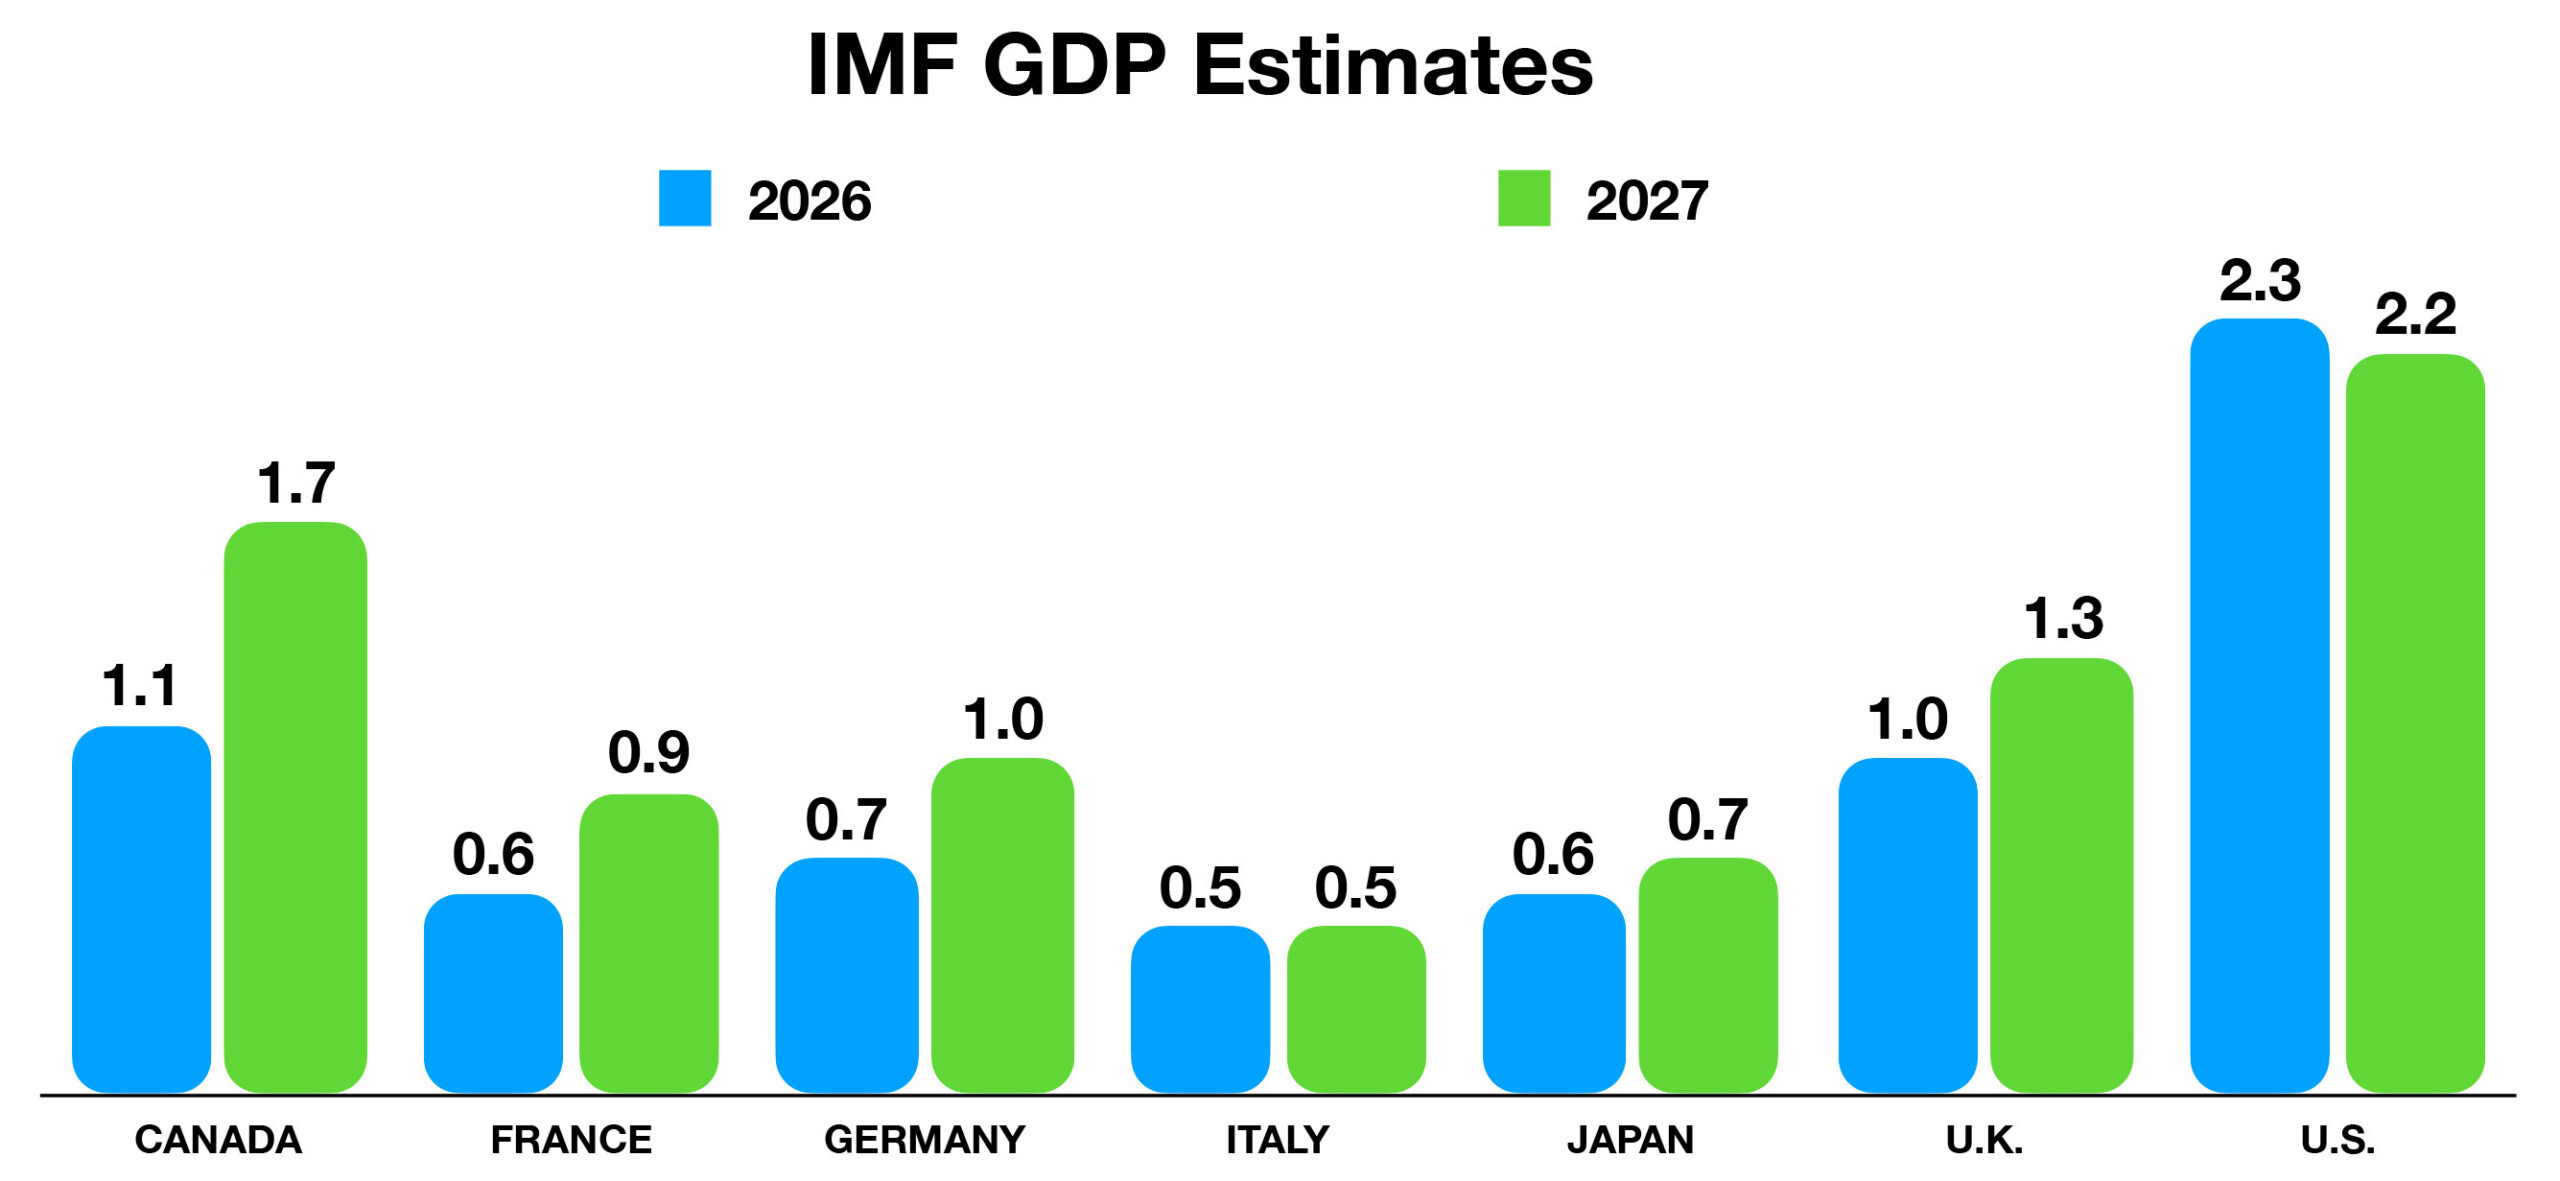
U.S. Leads In Projected Global Growth – Global Economy
Of all of the developed countries globally, the United States is projected to have the leading economic expansion as measured by Gross Domestic Product (GDP), this year and in 2027. Looking forward, the demographical makeup of the U.S., along with ongoing technological advancements, will allow the U.S. to grow faster than other developed countries. Data from the International Monetary Fund (IMF) allows for global economic projections continuously.

Emerging economies, such as India, China, Saudi Arabia and Indoneisia, are estimated to have faster economic growth rates than the U.S., primarily due to younger populations and demographical factors.
An aging population in European counties is saddling current and future workers with enormous pension obligations and a shrinking workforce. An elevated unemployment rate of 6.3% in the European Union (EU) also weighs on European expansion and productivity. Japan and Canada are also facing expansion constraints, due to employment challenges and fiscal initiatives hindering economic growth.
The International Monetary Fund (IMF) bases its Gross Domestic Product (GDP) estimates primarily on data reported by individual member countries’ national statistical agencies, which it then standardizes and projects using its own economic analysis. Growth estimates are vital for the projection of energy and capital needs as developed and emerging economies either grow or contract year to year.
Source: International Monetary Fund